
Abstract:
- Anthropic is the second company valued over $1 trillion to issue stock on the U.S. exchange this year, raising capital of $107.3 billion in its debut (including a $26 billion private placement) as the biggest IPO on record. The company is valued at roughly $1.5 trillion and priced at $83 per share.
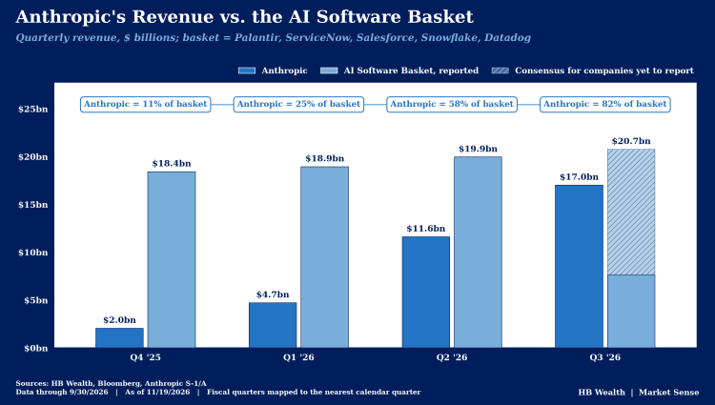
- As the first pure-play AI frontier model builder to issue public equity, Anthropic will offer a real-time public lens for investors to view fundamentals of the AI frontier. So far, the company is experiencing remarkably rapid growth in revenue, but the path to profitability remains uncertain. Its $35.3 billion in past year revenues put the company around the 130th largest company in the United States ranked by revenue, slightly ahead of SpaceX.
- Yet, the company, much like 42% of US IPOs, including SpaceX, since 1980 (based on data from Jay Ritter at the University of Florida), operates at a loss. Profitability hinges on four possible avenues to boost sales and/or increase margins – increased adoption, token price hikes, lowering compute costs, and disrupting existing businesses to generate additional revenue. We review the current trends in each of these drivers.
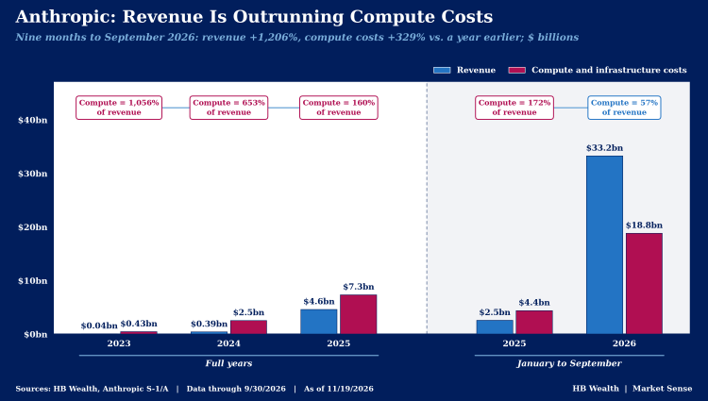
Anthropic’s IPO comes at a point of notable volatility around the AI trade but also coincides with a significant improvement in the company’s fundamentals. Based on the company’s S-1 filing for its November 19th IPO, Anthropic posted $17 billion in revenues in 3Q, up from $1.4 billion in the year ago quarter, marking a 1200%+ gain in the first nine months of 2026 versus the comparable period in 2025. Still, the company remains unprofitable – the company’s $1.3 billion operating loss was driven primarily by $18.8 billion of compute costs on $33.2 billion revenues in the first nine months of the year. A $94 billion loss on the fair value of convertible notes, derivatives and SAFEs pushed the net loss to over $104 billion. While those convertible notes will be redeemed for equity, eventually removing the loss from Anthropic’s income statement and raising separate dilution concerns, operational issues remain.
Net profit didn’t prevent SpaceX – which posted a $4.9 billion net loss in 2025 ahead of its June IPO — from a positive market reception, even though unprofitable IPOs have typically underperformed profitable ones over the longer-run (based on data from Jay Ritter at the University of Florida). Nonetheless, as we outlined in our Market Sense note on June 15th, a flip to profitability is usually key to sustained success for IPOs. Anthropic’s path to profitability hinges on four possible avenues to boost sales or increase margins – increased adoption, token price hikes, lowering compute costs, and disrupting existing businesses to generate additional revenue.
Model Adoption Leaves Plenty of Room for Growth, But How Much Goes to China?
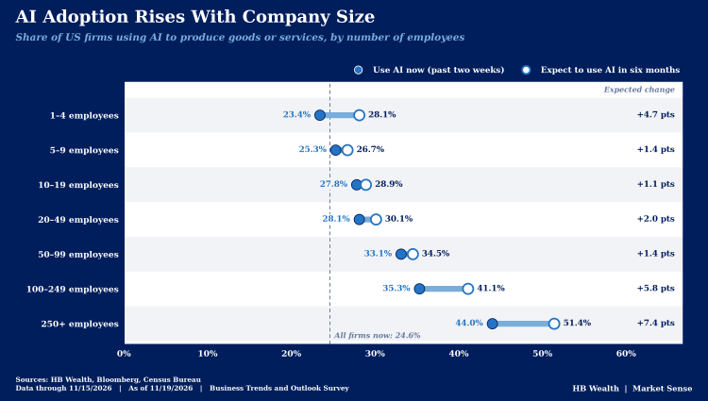
Adoption has been surging, but there’s plenty more room for growth. Utilization by US businesses is rising rapidly – just under 25% of U.S. companies used AI models over the past two weeks, up from a shade under 10% as recently as October 2025. Unsurprisingly, the largest cohort of firms have been the quickest to adopt AI and are expected to have the biggest acceleration in use – currently, 44.0% of firms with more than 250 employees use AI and that could jump to 51.4% over the next six months based on a survey from the Census Bureau. That would be the first grouping to cross the 50% mark with companies of 100-249 and 50-99 employees hitting 41.1% and 34.5% adoption in the next six months, respectively. Still, extremely small firms are planning to up their usage with companies of just 1-4 employees expected to increase adoption from 23.4% to 28.1%.
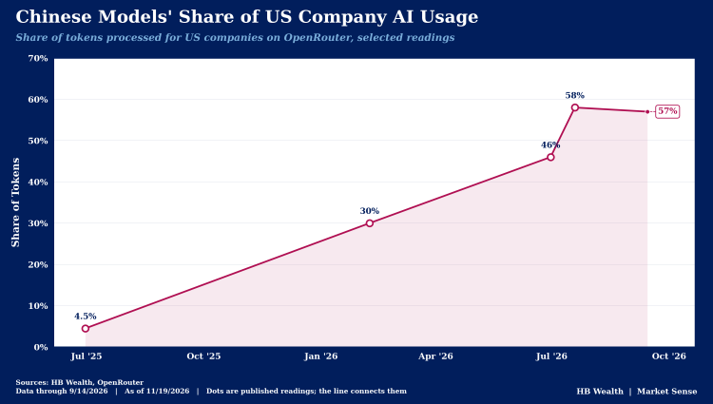
Nonetheless, those figures leave plenty of room for upside. However, the question is how much share will cheaper Chinese models take from frontier providers like OpenAI and Anthropic? Usage of Chinese models has likewise been surging, currently comprising just over 55% of US token usage and up from roughly 5% in August 2025. However, these models’ percentage of US company token usage has plateaued as of late. Likewise, a regulatory overhang remains – given the national security implications of model development and data security concerns, moves to limit usage of Chinese models could emerge at both the congressional and company level.
Token Demand Surging, Do Frontier Providers Have Pricing Power?
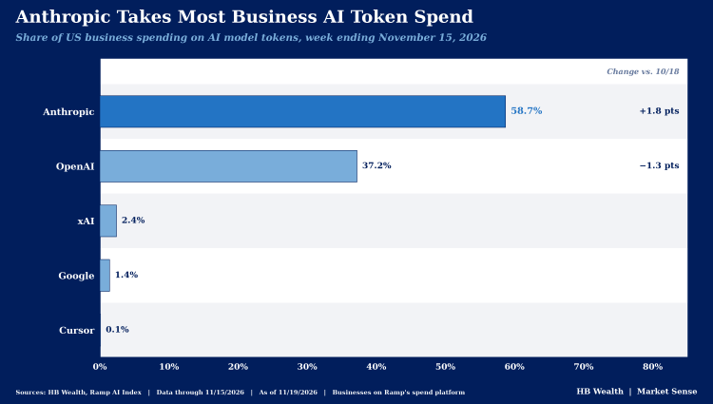
Token usage – essentially the volume of sales – is surging with Alphabet processing 3.2 quadrillion tokens a month as of May 2026. However, token prices keep dropping, now down 62% year-over-year as cheaper alternatives and competitive pressures keep token costs suppressed. Still, frontier models dominate business spending on AI (based on data from Ramp) and companies have proven willing to spend more per-user. Currently, Anthropic gets 58.7% of business token spend to OpenAI’s 37.2%. Those companies have likewise ramped up spending per-employee with the Ramp AI index noting that companies are now spending $16.32 per-user – up 158% since January. The question remains – will OpenAI and Anthropic be able to push business price hikes given the emergence of cheaper alternatives from China and elsewhere?
Compute Costs Eating Away at Operational Profit
Compute costs – the price of renting GPUs for training and inference – has been rising and is the main reason Anthropic is still operationally unprofitable. However, Anthropic’s revenues have at least been accelerating faster than compute costs, providing some relief. Based on the company’s S-1 filing, revenues grew over 1200% while compute costs rose 329% in the most recently reported nine-month stretch versus the comparable period a year ago. However, compute costs per dollar of revenue has been steadily dropping – it was over 170% in the first nine months of 2025 versus 57% through September 2026. That’s all thanks to the revenue surge, though it behooves Anthropic to search for suitable alternatives for compute. In fact, Anthropic and OpenAI have launched efforts to build their own chips in order to ease some of these pressures.
Disruption – Anthropic’s Profitability Trump Card
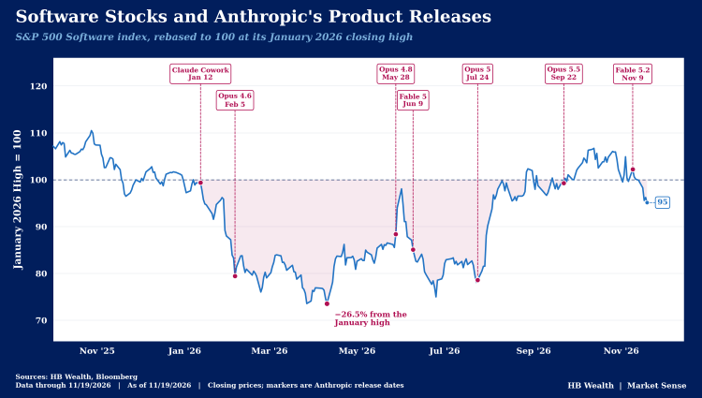
Fears that AI could displace legacy software as a service (SaaS) business models caused significant volatility across software stocks earlier this year and ultimately, Anthropic and OpenAI could find areas of automation that displace existing businesses – leading to significant boosts in profitability. From the January high to its ultimate low, the S&P 500 software index fell 26.8% following Anthropic’s launch of agentic AI tools and plugins that stoked fear that AI agents would eventually disrupt the seat-pricing model of software companies. While those fears appear largely premature and overblown, they offer a view into a potential path toward additional profitability for Anthropic. If models eventually become advanced and specialized enough to disrupt legacy businesses, the company could attempt to monetize such services rather than merely provide models to businesses that boost efficiency. Such a path has been carved out by current tech behemoths – from Amazon leveraging its logistical expertise from its online bookseller days to turn into a retail giant to Alphabet using its expertise in search to become a key cloud provider and displace old data management systems. While it’s hard to conceive what future key segments Anthropic and OpenAI will spawn, it’s more likely than not their offerings will expand beyond providing AI tools.
Past Work on IPOs
IPOs are Risky and Public Market Investors are Often Left Holding the Bag
It’s Not Just Mega-IPOs, US Issuance Pipeline is Exceptionally Strong
Can SpaceX Break the Post Pandemic IPO Curse?
A Deep Dive: Will 2026’s Unicorns Pierce the Market’s Armor or Prove to Be Trusty Steeds?
Disclosure: HB Wealth is an SEC‑registered investment adviser. The information reflects the author’s views, opinions, and analyses as the publication date. The information is provided for informational purposes only and does not constitute an offer to sell or a solicitation of an offer to buy any investment product. This information contains forward-looking statements, predictions, and forecasts (“forward-looking statements”) concerning the belief and opinions in respect to the future. Forward-looking statements involve risks and uncertainties, and undue reliance should not be placed on them. There can be no assurance that forward-looking statements will prove to be accurate, and actual results and future events could differ materially from those anticipated in such statements. The information does not represent legal, tax, accounting, or investment advice; recipients should consult their respective advisors regarding such matters. Certain information herein is based on third-party sources believed to be reliable, but which have not been independently verified. Past performance is not a guarantee or indicator of future results; inherent in any investment is the risk of loss.