
Abstract:
- As inflation remains top of mind, fixed income investors may be tempted by TIPS, but there is considerable risk in this approach.
- The history of TIPS performance during inflation spikes shows how inconsistent returns can be. Over the 22-year life of the popular ETF for TIPS exposure, “TIP”, performance has often failed to match CPI.
- TIPS often don’t perform how a retail investor may expect. We identify 4 criteria that an investor needs to meet to justify a position.
- Often overlooked, short duration credit can be an unsung hero in helping fixed income investors mitigate the impact of inflation.
- An overweight to short duration credit and one-off use of TIPS only when specific conditions are met can help build an inflation-resilient portfolio in fixed income.
TIPS Often Struggle to Protect from Inflation In the Way that Investors Intend
The history of TIPS performance during inflation spikes shows how inconsistent returns can be in different environments. Over the 22-year life of the popular ETF for TIPS exposure “TIP”, performance has often failed to meet the commonly held expectation that TIPS should provide a return at least equal to that of CPI. Indeed, TIPS only kept pace in instances when real yields fell with moves dominated by duration, such as 2007-08 when real yields fell by 77bp. In that instance, TIPS materially outperformed. However, when real yields rose, such as in 2020-22, TIPS performance lagged CPI. When CPI rises, the principal value of TIPS is adjusted by the same percentage, which is referred to as accretion. TIPS have delivered that accretion, but that benefit is only felt by investors when policy pushed real yields lower. Nearly all of the relationship between TIPS performance and CPI can thus be attributed to changes in real yields.
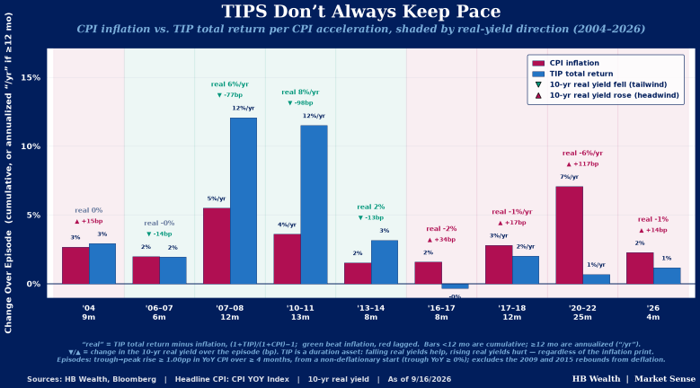
Most that seek TIPS for inflation protection focus on the erosion of buying power problem, but TIPS are effectively both long inflation and long duration, and duration can be a significant drag on returns in an inflationary environment. A 10-year TIPS carries roughly 9 years of duration, and retail TIPS exposure through ETFs gets dominated by that duration. A good example of how duration eroded the return for TIPS was in 2022. In that year, the inflation accretion was worth ~8% and the real-rate repricing cost ~17%. In theory, the hedge worked as designed, but because of the vehicle/channel, investors still lost money. A solution to this is to be long TIPS vs short duration matched nominal Treasuries to isolate inflation and strip out real rates, but such a strategy is effectively unavailable to individual investors.
While duration is the most straight-forward issue with TIPS for individual investors, there are also a range of mechanical issues that compound to be equally impactful in limiting the effectiveness of the strategy. First, and often the most overlooked, is phantom income. The accretion from inflation adjustments is taxed as ordinary income in the year it is accrued, which, depending on the coupon, can provide negative after-tax cash flow in a high-CPI year. That can be mitigated by holding in tax-deferred accounts.
Second, TIPS are issued at par and then the principal is adjusted based on changes in CPI. What is guaranteed by the treasury at maturity is original par, which does not factor in inflation adjustments. This means that buying TIPS with a large inflation factor from previous adjustments exposes the investor to loss of principal in the event of a deflationary environment. Deflation is far from base case in the current state, but even a small chance of principal loss on a Treasury security makes the math tough to justify paying for a sizeable existing inflation factor. The index ratio (size of the inflation factor vs initial par value) can be minimized by purchasing TIPS at, or close to, new issue.
Finally, and for an even deeper technical issue, the index ratio references CPI from three months prior, so TIPS structurally under-protect against a sudden spike in real time. The CPI measure from which the indexing is derived is non-seasonally adjusted, so accrual has seasonal patterns that institutional investors price that often skews pricing for retail buyers. Combine those mechanics with a market with securities held predominantly in a small number of index vehicles, and investors are left with greatly dampened liquidity due to the relatively small amount of float remaining.
All of this points to a narrow use-case for individual TIPS – held to maturity, bought at or near new issue, in a tax-deferred account, matched to a known liability at a known date. Under those four conditions they are the only instrument that delivers a contractually certain real return, duration becomes irrelevant against a matched liability, the floor is at-the-money, this tax problem is gone, and you never trade the CUSIP. However, meeting these four conditions is relatively uncommon, resulting in frequently disappointing performance. For investors meeting those criteria, we are at a historically attractive entry point at roughly 2.4% real yield for 10-year TIPS.
Short Duration Credit Has Inflation Hedge Qualities Too
A potentially more effective option for fixed income investors concerned about inflation risk is short duration credit. A short-duration credit holding is a reinvestment option more than it is a direct inflation hedge. Investors give up locked-in yield for the right to frequently reinvest at higher yields after an inflation shock, given the shorter maturity focus of the strategy. A prime example was in 2022 where T-Bills outperformed TIPS as well as any area of fixed income with a measurable sensitivity to rates, and that is with a vehicle that doesn’t even have added credit spread.
In an inflationary environment, nominal inflation-driven revenue growth can be a support to corporate bond fundamentals. Absent a major default spike, that boost to credit fundamentals helps to keep spreads from widening meaningfully from their historically tight levels. Being able to frequently reinvest maturities alongside a boost to fundamentals makes short duration credit an exposure worth considering for those concerned about inflation, even if it’s not directly a hedge.
Even a modest repricing of spreads hurts longer duration credit disproportionally. A theoretical 50bp spread move costs roughly 3.5% on a bond with seven years of spread duration and 0.75% on one with 1.5 years. Short credit’s advantage is that moves in spreads and moves in rates both hurt less.
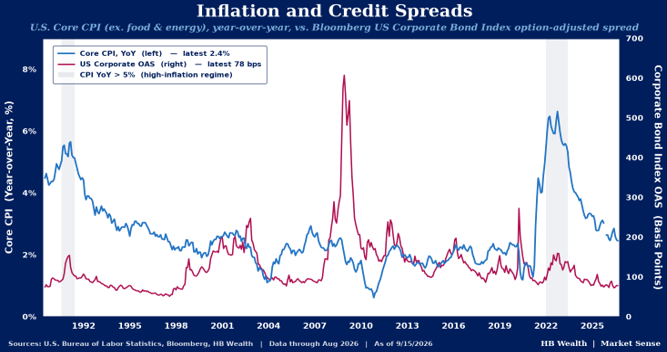
In the current environment, short duration credit is better suited as an overweight position rather than a wholesale portfolio pivot. The reinvestment option that adds value when inflation drives rates higher also becomes a headwind when short rates fall as bond maturities are reinvested at decreasing yields. The curve is paying you to extend duration these days, and keeping a portion of a portfolio in the intermediate part of the curve helps to dodge much of the Fed-driven short-end volatility that is not expected to subside anytime soon.
While inflation fears may give bond investors a general sense of uncertainty, there are ways to position portfolios to support returns in an inflationary environment. Strictly within the confines of the fixed income portfolio, an overweight to short duration credit and one-off use of TIPS when specific conditions are met can play a role in broader asset allocation efforts. Alongside exposures to commodities in the shorter term, and real estate, private assets and equities over the long term, these portfolio tilts within fixed income can help build an inflation-ready portfolio.
Disclosure: HB Wealth is an SECregistered investment adviser. The information reflects the author’s views, opinions, and analyses as the publication date. The information is provided for informational purposes only and does not constitute an offer to sell or a solicitation of an offer to buy any investment product. This information contains forward-looking statements, predictions, and forecasts (“forward-looking statements”) concerning the belief and opinions in respect to the future. Forward-looking statements involve risks and uncertainties, and undue reliance should not be placed on them. There can be no assurance that forward-looking statements will prove to be accurate, and actual results and future events could differ materially from those anticipated in such statements. The information does not represent legal, tax, accounting, or investment advice; recipients should consult their respective advisors regarding such matters. Certain information herein is based on third-party sources believed to be reliable, but which have not been independently verified.
References to specific securities, asset classes, investment strategies, exchange-traded funds (including TIPS-related ETFs), or market sectors are provided for illustrative purposes only and should not be construed as recommendations. Any discussion of Treasury Inflation-Protected Securities (TIPS), short-duration credit, Treasury securities, corporate bonds, or other fixed income investments is intended solely to explain market concepts and potential risks and opportunities.
Investing in fixed income securities involves risks, including interest rate risk, credit risk, liquidity risk, duration risk, downgrade risk, and the potential loss of principal. Investments associated with data centers, artificial intelligence infrastructure, asset-backed securities, structured products, project finance, and other specialized credit instruments may involve additional risks and complexities that can result in increased volatility or principal loss.
Credit ratings are opinions regarding creditworthiness and are subject to change at any time. Ratings are not guarantees of future credit quality, performance, or the avoidance of defaults.
Indexes are unmanaged, cannot be invested in directly, and do not reflect the deduction of fees, expenses, or transaction costs. Sources for market, economic, and performance data include third-party providers believed to be reliable; however, accuracy and completeness cannot be guaranteed.